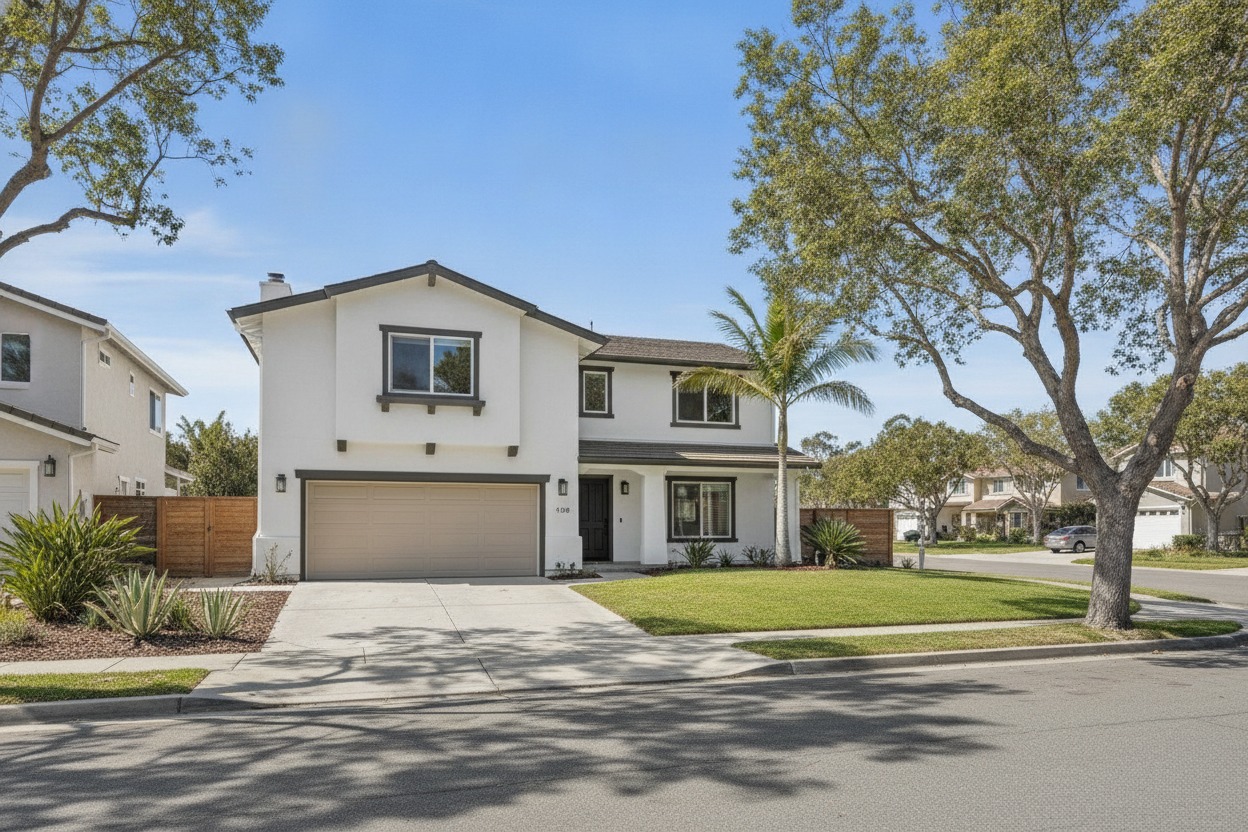
Selling My Huntington Beach Condo Before Buying: Your Questions, Answered Plainly
Quick answer
For most owners, selling my Huntington Beach condo before buying is the lower-risk path. The detached single family median in Huntington Beach is $1,649,500 (226 sales, 90 days ending 2026-09-30, CRMLS). Move-up buyers typically need $340,000 to $600,000 in down payment and closing costs. Carrying both mortgages costs $3,000 to $6,000 a month. Selling first protects your budget and strengthens your offer.
- The detached single family median in Huntington Beach is $1,649,500 (CRMLS, Sep 30, 2026).
- Orange County median days on market was 46 days in late September 2026, so a well-priced condo can reach escrow in roughly 6 to 8 weeks.
- Dual carrying costs at your price point run $3,000 to $6,000 per month if escrows overlap.
- HOA transfer fees, payoff letters, and any pending special assessments reduce your net proceeds before you close.
Last verified: October 2026 · Sources: California Board of Equalization: Change in Ownership FAQs, IRS Topic 701: Sale of Your Home
Selling my Huntington Beach condo before buying a detached home is the question at the center of every move-up decision in this city. The answer depends on your equity, your loan balance, your HOA obligations, and how much carrying cost you can absorb if the timing slips. This is not a one-size answer.
It is a math problem with a deadline. Gantry Wilson has served Huntington Beach and Orange County since 2004 and has personally sold more than 300 homes here. The framework below is built on real local numbers so you can make a clear decision in the next 0 to 6 months.
The trade-up math: condo equity versus detached down payment
Start with what you will actually pocket. Take your expected sale price, subtract your mortgage payoff, subtract 5 to 6 percent for commission, subtract roughly 1 to 2 percent for closing costs, and subtract any HOA transfer fees or special assessments.
On a $1,100,000 condo sale with a $400,000 balance, that math leaves you somewhere between $580,000 and $620,000 in net proceeds before taxes.
The detached single family median in Huntington Beach is $1,649,500 (226 closed sales, 90 days ending 2026-09-30, CRMLS). If you are targeting a home in the $1.7M to $2.4M range, a 20 percent down payment alone runs $340,000 to $480,000.
Add 1 to 2 percent in buyer closing costs and you are looking at $360,000 to $530,000 out of pocket before you move in.
That math shows why your condo equity is not optional. It is the engine. Without those proceeds, you either need bridge financing, a sale contingency, or proof you can carry two mortgages. Each of those paths adds cost and complexity. Knowing your net number first is the only way to know which path is realistic.
Orange County had 5,061 active listings and 1,771 pending contracts in late September 2026. That is a market with real inventory but not a flood of it. Detached homes in the $1.7M to $3M range in Huntington Beach move, but they do not sit forever waiting for a contingent buyer.
Your equity position determines how competitive you can be.
The county-wide detached single family median is $1,485,000 (3,204 closed sales, 90 days ending 2026-08-25, CRMLS). Huntington Beach runs above that county line, which means your condo sale needs to be priced and marketed precisely to generate the proceeds your next purchase requires.
Sell first or buy first: contingency and bridge-loan trade-offs
A sale contingency protects you. It says you will buy the detached home only after your condo closes. Sellers in the $1.7M to $3M range often have multiple offers, and a contingent offer is weaker than a clean one. You may need to offer more, or accept less favorable terms, to get a seller to accept that contingency.
Bridge financing is the other tool. A bridge loan lets you borrow against your condo equity before it sells, so you can make a clean offer on the detached home. The cost is real: bridge loans typically carry rates above the standard 30-year fixed, which was 7.28 percent for the week ending October 1, 2026.
Add origination fees and you are paying for the privilege of moving fast.
A rent-back agreement is a third option. You sell your condo, close, and then rent it back from the new owner for 30 to 60 days while you close on the detached home. This keeps your proceeds liquid and your offer clean. It does require the condo buyer to agree, and not every buyer will.
For more on how rent-backs work in practice, see Rent-Back When Selling and Buying in Huntington Beach: The Decision, Step by Step.
Rate-lock risk is real if you buy before selling. If your condo takes longer than expected to close, your rate lock on the detached home may expire. Extending a rate lock costs money, and rates can move in either direction. At 7.28 percent on a $1.4M loan, every eighth of a point matters.
The cleanest path for most move-up buyers at this price point is to list the condo, get it into escrow, and then make an offer on the detached home with a short contingency period or a rent-back request. That sequence keeps your equity working and your offer as strong as possible.
"Attention to detail and super friendly!"
Mike Estrada
HOA exit and special assessments: what you owe before closing
Condos in Huntington Beach almost always carry an HOA. Before you list, you need three documents: the HOA payoff letter showing any unpaid dues, the transfer disclosure package the buyer is entitled to receive, and confirmation of any pending or approved special assessments.
These are not optional, and they affect your net proceeds directly.
A special assessment is a charge the HOA levies on all owners to cover a major repair or reserve shortfall, things like roof replacement, elevator work, or seismic retrofitting. If your HOA has approved one and you have not paid it, the buyer will find it in the disclosure documents.
It either reduces your net proceeds or becomes a negotiating point.
HOA transfer fees vary by association. They typically run $200 to $600 but can be higher in larger complexes. Some associations also charge a document preparation fee and a move-out fee. Add these to your closing cost estimate before you set a price expectation.
Condo communities in Huntington Harbour, for example, often have more complex HOA structures because of shared waterways, docks, and common areas. If your condo is in a waterfront complex, confirm whether the HOA covers seawall maintenance or dock repairs, because a pending assessment there can be significant.
For more on condo insurance in the Harbour, see Insure My Huntington Harbour Condo: A Risk-Aware Owner’s Read.
The practical checklist before you list: request the HOA payoff letter, review the reserve study for funded status, confirm no pending litigation against the HOA, and get the transfer fee schedule in writing. Buyers and their lenders will ask for all of this. Having it ready shortens escrow and removes surprises.
Coastal insurance, flood zones, and property-tax timing in Huntington Beach
When you move from a condo to a detached home in Huntington Beach, your insurance picture changes. Condo policies typically cover the interior only, with the HOA master policy covering the structure. A detached home requires a full homeowners policy covering the structure, contents, and liability.
Coastal proximity can push annual premiums higher than inland properties.
Some detached homes in Huntington Beach, particularly near the Bolsa Chica wetlands, Huntington Harbour channels, or low-lying coastal areas, fall within FEMA flood zones. If the home you are buying requires flood insurance, budget for it separately.
Flood policies through the National Flood Insurance Program or private carriers add to your monthly carrying cost and should be confirmed before you make an offer.
Property taxes reset at purchase under Proposition 13. Your new tax bill will be roughly 1.25 percent of the purchase price per year, which includes the 1 percent base rate plus local voter-approved assessments. On a $2,000,000 purchase, that is about $25,000 a year, or roughly $2,083 a month added to your payment.
Factor this into your affordability before you set your target price range. For specifics on how reassessment works, the California Board of Equalization has a plain-language FAQ.
California’s capital-gains home-sale exclusion can reach $250,000 for a qualifying single filer and $500,000 for married couples filing jointly on the sale of a primary residence. If you have owned your condo long enough to have significant appreciation, this exclusion may apply.
Confirm your eligibility and the specifics with your CPA or tax advisor before you close, because the rules have holding-period and use requirements. The IRS Topic 701 page is a good starting point.
Some communities in Huntington Beach also carry Mello-Roos assessments, which are additional tax charges tied to community facilities bonds. Brightwater and some newer areas carry them.
Ask your agent to confirm whether the detached home you are targeting has a Mello-Roos line on the tax bill before you finalize your budget.
"Gantry put us first, letting us lead the house hunting journey. Great knowledge of the industry’s ins and outs. His word is gold"
Shawn Ferguson
Orange County inventory and days on market: why timing matters now
Orange County had 5,061 active listings and 1,771 pending contracts in late September 2026. That is a market with meaningful supply but not a buyer’s market. Sellers of well-priced detached homes in Huntington Beach are still getting close to asking price.
The Orange County median days on market was 46 days in late September 2026. In Huntington Beach specifically, detached single family homes had a median of 19 days on market over the 90-day period ending September 30, 2026 (CRMLS).
That is a faster pace than the county overall, which matters for both your condo sale and your detached-home search.
The 30-year fixed mortgage rate was 7.28 percent for the week ending October 1, 2026. At that rate, a $1.4M loan carries a principal and interest payment of roughly $9,600 a month. That number shapes what you can afford on the detached side and how long you can sustain dual carrying costs if the timing overlaps.
Orange County sales were down about 2 percent year over year in September 2026. That slight softening does not mean prices are falling in Huntington Beach. The year-to-date median for detached homes in the city rose 11 percent compared to 2024. Volume is flat, but values are holding.
The practical implication: your condo will likely sell in 6 to 8 weeks if it is priced correctly. The detached homes you want are moving in under 3 weeks at the median. That gap in pace is the core timing risk. You need your condo in escrow before you make a serious offer, or you need a bridge plan in place.
| Metric | Value | Source |
|---|---|---|
| OC active listings (late Sept 2026) | 5,061 | CRMLS, Oct 2026 |
| OC median days on market | 46 days | CRMLS, Sept 2026 |
| HB detached median days on market | 19 days | CRMLS, Sep 30, 2026 |
| HB detached SFR median (90-day) | $1,649,500 | CRMLS, Sep 30, 2026 |
Carrying costs and overlapping escrows: the real-world risk
If your condo escrow and your detached-home escrow overlap, you carry both sets of costs at the same time. On the condo side, that means your existing mortgage, HOA dues, insurance, and property taxes. On the detached side, that means your new mortgage payment, homeowners insurance, and property taxes.
At your price point, the combined overlap typically runs $3,000 to $6,000 per month.
Escrow in Huntington Beach closes in about 30 days after opening. That means if you open escrow on the detached home before your condo closes, you are looking at roughly one month of dual payments. If the condo escrow runs long for any reason, that overlap extends.
Budget for 60 days of dual carrying costs as a conservative cushion.
A rent-back on your condo sale is one way to compress the overlap. You close on the condo, collect your proceeds, and rent the unit back from the new owner for 30 to 60 days while you close on the detached home.
The rent you pay is typically set at the buyer’s new mortgage payment divided by 30, so it is not free, but it is usually less than carrying two full mortgages.
Bridge financing solves the sequencing problem differently. You borrow against your condo equity before it sells, use those funds for the detached-home down payment, and repay the bridge loan when the condo closes. The cost is the bridge loan rate plus origination fees.
At current rate levels, that adds up quickly, so run the numbers before committing.
The break-even question is simple: how many months of overlap can you absorb without straining your reserves? If the answer is one month, sell first. If you have six months of reserves and a strong pre-approval, a contingency or bridge may be worth the cost to move faster on a detached home you really want.
Selling my Huntington Beach condo before buying: what to do next
The first step is a net-proceeds estimate. Pull your mortgage statement, estimate your condo’s current value based on recent comparable sales, and run the math: sale price minus payoff, minus 5 to 6 percent commission, minus 1 to 2 percent closing costs, minus HOA transfer fees and any known assessments.
That number is your equity budget for the next purchase.
The second step is a pre-approval for the detached-home price range. Your lender needs to know your condo is either sold or contingent before fully underwriting the new loan. Get the pre-approval letter in hand before you start making offers.
It tells you exactly what you can borrow at current rates and what your monthly payment will be at different price points.
The third step is deciding on your sequencing strategy: sell first with a rent-back request, use a sale contingency on the detached home, or arrange bridge financing. Each has a different cost and a different risk profile.
The right answer depends on your reserves, your timeline, and how competitive the detached home market is in your target neighborhood.
Once you have those three pieces, the execution is straightforward. List the condo, price it to move in 30 days or less, and start your detached-home search in parallel. When the condo goes into escrow, you have a real number and a real timeline to work with. That is when you make your move on the detached side.
The 0-to-6-month window is the right frame for this decision. Rates are not dropping dramatically in the near term, inventory in Huntington Beach is tight but not frozen, and your condo equity is real money sitting in an asset you are ready to move out of.
The longer you wait, the more the detached-home market can move away from you. For a deeper look at how contingency offers work in Orange County, see Orange County Offer Contingencies and Earnest Money: How to Decide with Confidence.
Selling and buying at the same time
Map out your sell-and-buy move before you list
One call covers your net proceeds, your next payment, and how to bridge both sides without owning two homes or none.
Book my sell-and-buy strategy call
Prefer to talk now? Call or text 714-500-7797 · Serving coastal Orange County since 2004
Questions clients ask about selling my Huntington Beach condo before buying
Can I buy a detached home in Huntington Beach without selling my condo first?
Yes, but it requires either a sale contingency, bridge financing, or proof you can carry both mortgages at the same time. A sale contingency weakens your offer in a competitive market. Bridge financing adds cost on top of an already elevated rate environment. If you have the reserves to carry both payments for 60 to 90 days and a strong pre-approval, buying first is possible. Most move-up buyers at this price point find that selling first, or getting the condo into escrow first, produces a cleaner and less expensive outcome.
How much will I net from selling my condo after the mortgage, commission, and HOA fees?
The formula is straightforward: sale price minus your mortgage payoff, minus 5 to 6 percent commission, minus 1 to 2 percent in closing costs, minus HOA transfer fees and any special assessments. On a $1,100,000 sale with a $400,000 balance, you might net $580,000 to $620,000 before any tax considerations. The exact number depends on your payoff balance, your HOA’s fee schedule, and whether any assessments are pending. Run this calculation before you set your detached-home budget.
What if my condo is still in escrow when I close on the detached home?
You carry both sets of costs until the condo closes. At your price point, that overlap typically runs $3,000 to $6,000 per month, covering two mortgage payments, two insurance policies, HOA dues on the condo, and property taxes on both properties. A rent-back agreement on the condo sale can reduce the overlap by giving you 30 to 60 days after your condo closes to finish the detached-home escrow. Budget for at least 60 days of dual costs as a conservative cushion regardless of which path you choose.
Will my property taxes jump when I buy the detached home?
Yes. Proposition 13 reassesses the property-tax base at the time of purchase. Your new annual tax bill will be roughly 1.25 percent of the purchase price, which includes the 1 percent base rate plus local voter-approved assessments. On a $2,000,000 purchase, that is about $25,000 per year, or $2,083 per month added to your housing cost. Some communities in Huntington Beach also carry Mello-Roos assessments on top of that. Confirm the full tax picture on any specific property with your CPA or tax advisor before you finalize your budget.
How long does it take to sell a condo in Huntington Beach right now?
The Orange County median days on market was 46 days in late September 2026, but detached homes in Huntington Beach specifically were moving at a 19-day median over the same period. Condos can move faster or slower depending on price, condition, HOA reputation, and pending assessments. A well-priced condo in good condition with clean HOA financials can realistically be in escrow within 3 to 4 weeks of listing. That timeline is tight enough to sequence with a detached-home search if you start both at the same time.
Should I worry about a special assessment on my condo before I sell?
Yes, absolutely. Check your HOA records for any pending, approved, or planned special assessments before you list. If one is coming, it reduces your net proceeds and may slow the sale because buyers and their lenders will see it in the disclosure documents. Disclose it upfront. Buyers will find it during due diligence regardless, and transparency avoids renegotiation late in escrow. If the assessment is large, factor it into your net-proceeds estimate and adjust your detached-home budget accordingly before you start your search.
What to do right now
Here is what to do right now. Pull your mortgage statement and get a current value estimate on your condo. Run the net-proceeds math using the formula in this article. Then call your lender and get a pre-approval letter for the detached-home price range you are targeting. Those two numbers, your net proceeds and your borrowing capacity, define your actual budget. Once you have them, the sequencing decision becomes clear. If you are ready to map out the full sell-and-buy plan with real Huntington Beach numbers, book a strategy call at https://gantry.me/TalkToGantry or call 714-500-7797. Gantry Wilson, Gantry Wilson Group, Real Brokerage, DRE 01412779.
The next step
Ready to talk through your Huntington Beach move?
Tell me where you are in the process and I will map out your options, your numbers, and your timing. 15 minutes, zero pressure.
Schedule my free 15 minute call
Prefer to talk now? Call or text 714-500-7797 · Serving coastal Orange County since 2004
Know what Huntington Beach homes are really selling for
One short email each week: new listings, closed sales, and where prices are heading. Free, and easy to leave anytime.
Gantry Wilson · Gantry Wilson Group · Real Brokerage · Huntington Beach, CA · DRE# 01412779
Trusted. Local. Proven.