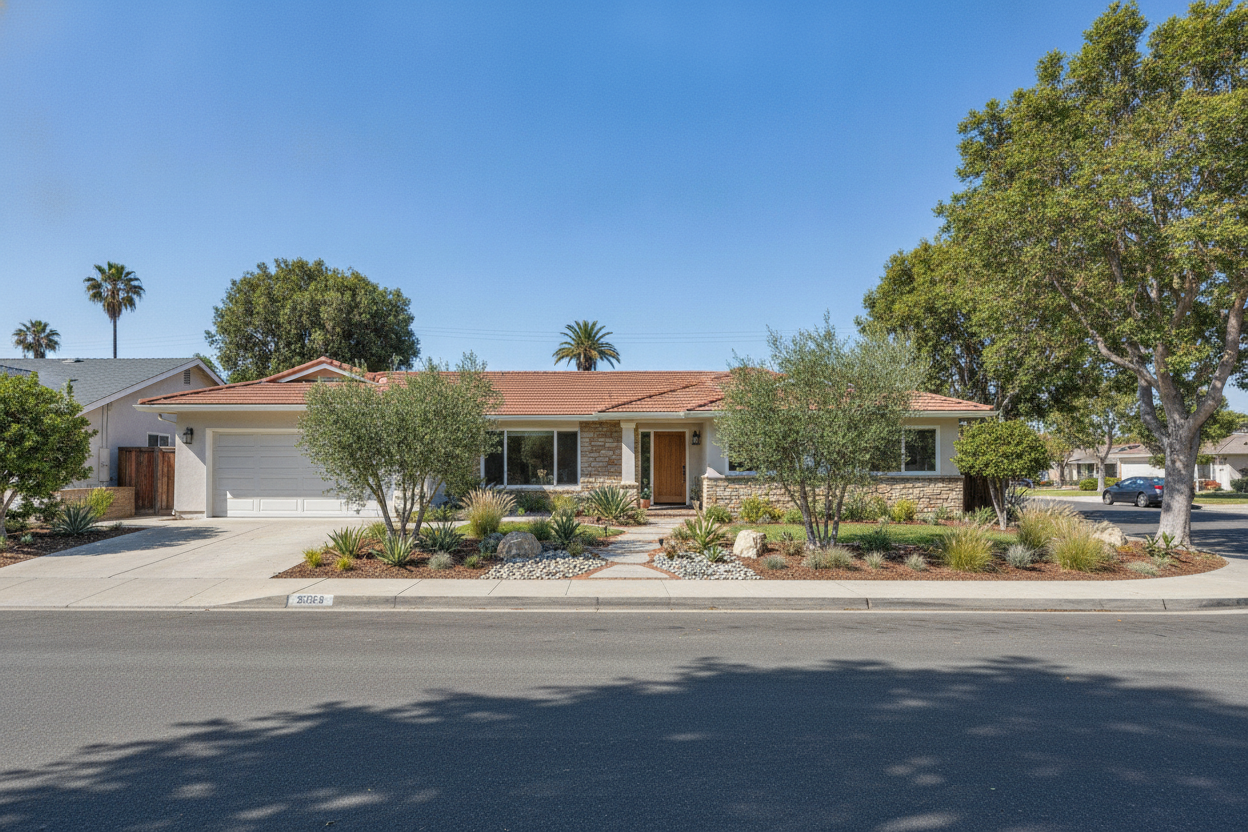
Buying a $2 Million Huntington Beach Home: A Clear Plan for Your Next Step
Quick answer
Buying a $2 million Huntington Beach home within 60 days of listing is realistic if you sequence it correctly. The detached single family median in Huntington Beach is $1,649,500 (226 sales, 90 days ending 2026-09-30, CRMLS). Homes at $2 million and above in Orange County sat at a 58-day median days on market in the October 2026 report. List first, open escrow on your purchase once you have an accepted offer, and line up bridge financing or a HELOC before you need it.
- The Huntington Beach detached single family median is $1,649,500 (CRMLS, 2026-09-30), so a $2M target is above median but well within the active market range.
- Orange County homes priced at $2M and above had a 58-day median days on market in the October 2026 report, giving you a realistic search window.
- Escrow in Huntington Beach closes in about 30 days or less after opening, so your 60-day clock is mostly listing time plus overlap.
- A bridge loan or HELOC can let you close on the purchase before your sale proceeds arrive, but confirm the math with a lender before you commit.
Last verified: October 2026 · Sources: HUD Fair Housing Resources
Buying a $2 million Huntington Beach home while your current place is still on the market is one of the most common move-up questions in coastal Orange County. The short answer is yes, it is doable, and the local market gives you more room than most people expect.
The detached single family median in Huntington Beach is $1,649,500 (226 sales, 90 days ending 2026-09-30, CRMLS), so a $2 million target puts you above median but squarely in an active price band. Gantry Wilson has served Huntington Beach and Orange County since 2004.
This piece lays out the sequencing, the financing options, and the local numbers so you can make a clear decision.
What the local market actually looks like at $2 million
The Huntington Beach detached single family median is $1,649,500, based on 226 closed sales in the 90 days ending September 30, 2026, per CRMLS. That median covers a wide range, from $840,000 to $6,900,000, so $2 million sits in a well-traded part of the market.
Homes sold at 98.5% of original list price on average, which means sellers are pricing close to market and buyers are not giving much away.
Orange County homes priced at $2 million and above had a 58-day median days on market in the October 2026 report. That number is the time from list to accepted offer, not the time to close escrow.
It tells you that a $2 million search in Huntington Beach typically takes about two months to find the right home and get an offer accepted.
Huntington Beach detached homes had a 19-day median days on market in the 90 days ending September 30, 2026, per CRMLS. That citywide figure is useful context, but the $2 million-plus segment moves more slowly than the overall market.
Plan your search timeline around the 58-day figure for that price band, not the citywide 19-day number.
The Seacliff area, which includes Old Seacliff, Holly-Seacliff, Edwards Hill, and the Bluffs, had a detached single family median of $2,858,150 (53 sales, 12 months ending 2026-09-30, CRMLS). Downtown Huntington Beach came in at $2,110,000 (62 sales, 6 months ending 2026-09-30, CRMLS).
Both neighborhoods put $2 million buyers in a real, active price band with genuine inventory.
Huntington Harbour interior homes, meaning no dock and no water view, had a median of $2,070,000 (27 sales, 12 months ending 2026-09-30, CRMLS). That is a useful benchmark if you are considering the Harbour area without paying waterfront prices.
Knowing where $2 million lands in each neighborhood helps you set a realistic search radius before you list.
| Neighborhood | Detached SFR Median | Sales Count |
|---|---|---|
| Huntington Beach citywide | $1,649,500 | 226 (90 days, CRMLS 2026-09-30) |
| Seacliff area | $2,858,150 | 53 (12 months, CRMLS 2026-09-30) |
| Downtown Huntington Beach | $2,110,000 | 62 (6 months, CRMLS 2026-09-30) |
| Huntington Harbour interior | $2,070,000 | 27 (12 months, CRMLS 2026-09-30) |
| Brightwater | $2,750,000 | 16 (12 months, CRMLS 2026-09-30) |
Separating listing time from escrow time
Most people think of a 60-day close as one continuous block. It is not. There are two distinct phases, and confusing them is where the plan falls apart. Phase one is listing time: how long it takes your home to go under contract. Phase two is escrow: the 30 days or less after both sides sign.
South Huntington Beach detached homes averaged 12 days to an accepted offer in the recent CRMLS period. Downtown numbered streets ran closer to 35 days. Your specific neighborhood matters more than the citywide average when you are building a timeline.
If your home goes under contract in 19 days and escrow takes 30 days, you have about 49 days from list date to your sale closing. That is your funding window. The question is whether you can open escrow on the purchase before your sale closes, and whether you can close the purchase without the sale proceeds in hand.
The answer depends on your equity, your income, and your backup financing. Those three things determine whether you are a contingent buyer, a bridge-loan buyer, or a cash-reserve buyer. Each path has different risks and different leverage at the negotiating table.
One more timing note: the 58-day median days on market for $2 million-plus homes in Orange County means your purchase search should start before you list, not after. You want to know the inventory, have toured the neighborhoods, and have a shortlist ready so you can move quickly once your home is under contract.
"Gantry put us first, letting us lead the house hunting journey. Great knowledge of the industry’s ins and outs. His word is gold"
Shawn Ferguson
Financing options for buying a $2 million Huntington Beach home
A $2 million purchase at the current 30-year fixed rate of 7.40%, reported by the Freddie Mac survey on October 8, 2026, means a meaningful monthly payment. At 20% down, the loan is $1.6 million. At 7.40%, the principal and interest payment alone is roughly $11,000 a month.
Add property taxes at about 1.25% of assessed value and any HOA dues, and the total monthly cost is real. Run those numbers with a lender before you commit to a price point.
A sale contingency lets you make an offer on the purchase that is conditional on your home selling first. Sellers at $2 million in a 58-day market are less likely to accept a contingency without a kick-out clause, which gives them the right to keep marketing and accept a better offer.
That is not a dealbreaker, but it is a negotiating reality you need to plan around.
A bridge loan is a short-term loan secured against your current home’s equity. It gives you cash to close the purchase before your sale proceeds arrive. Bridge loans carry higher rates than a standard mortgage, and they require strong income and equity to qualify.
Confirm the terms and costs with a lender before you count on this option.
A HELOC, or home equity line of credit, works similarly if you have enough equity and the line is already open. The key word is already. Opening a HELOC after you list is harder because lenders see the listing as a signal that the collateral is leaving.
If a HELOC is part of your plan, open it before you put your home on the market. Confirm the approach and timing with your lender before you rely on it.
Cash reserves are the cleanest path. If you have enough liquid assets to close the purchase without the sale proceeds, you can make a non-contingent offer and negotiate from a stronger position. Not every move-up buyer is in that position, but it is worth knowing your number before you rule it out.
What your sale price needs to do
If you are selling in the $900,000 to $1.4 million range and buying at $2 million, the gap between the two transactions is the core math. Your sale proceeds, after paying off your mortgage and closing costs, need to cover your down payment and leave enough reserve to qualify for the new loan.
Work that number backward from the purchase price, not forward from a hoped-for sale price.
Huntington Beach detached homes sold at 98.5% of original list price in the 90-day period ending September 30, 2026, per CRMLS. Pricing your home accurately from day one matters more than pricing high and cutting later. A price cut signals hesitation to buyers and can slow your sale at exactly the wrong moment.
South Huntington Beach detached homes sold at 100% of original list price in the same period. The northwest interior (zip 92647) had a detached single family median of $1,245,000 (47 sales, 90 days ending 2026-09-30, CRMLS).
Knowing where your home sits in the local price band helps you set a realistic net-proceeds figure before you make any commitments on the buy side.
Closing costs on the sale side in California vary; confirm the estimated figures with your escrow officer and agent before you commit. On the purchase side, closing costs vary as well; get a loan estimate from your lender early in the process. Both numbers need to be in your cash-flow model before you sign anything.
If your transaction involves capital gains, Prop 19 portability, or a 1031 exchange, the tax implications can affect how much of your sale proceeds you keep. Confirm the specifics with your CPA or tax advisor before you structure the deal.
"I am grateful for everything Gantry did for me in the sale of my house. He walked me through the process and helped me get top dollar. He was very quick to respond every time I had an issue or question. I appreciate his knowledge and professionalism. I would definitely recommend Gantry to anyone who is buying or selling a home."
Steven French
Coastal disclosures and what can slow a $2 million close
Huntington Beach is a coastal city, and that adds layers to any transaction. Natural hazard disclosures are required and cover flood zones, fire zones, and seismic hazard zones.
Homes near the Bolsa Chica wetlands, the Harbour channels, or the beach itself may sit in FEMA Zone AE, which requires flood insurance as a lender condition. That insurance cost needs to be in your monthly budget before you make an offer.
HOA documents are another timeline risk. Huntington Beach detached homes with an HOA carry a median fee of $280 a month (12 months ending 2026-09-30, CRMLS). If the home you are buying has an HOA, the seller must provide CC&Rs, bylaws, financials, and a reserve study.
Reviewing those documents takes time, and a weak reserve fund can affect your financing.
Permit history matters at this price point. A $2 million home in Huntington Beach often has additions, remodels, or accessory structures. If any of that work was done without permits, it can surface during inspection and create a negotiating issue or a lender condition.
Confirm permit history through the city and review any inspection findings carefully.
Additions and structural changes in the coastal zone may require a Coastal Development Permit from the California Coastal Commission in addition to city permits. That is a due-diligence item, not a dealbreaker, but it needs to be on your checklist.
Sewer lateral inspections, termite reports, and roof inspections are standard in Huntington Beach transactions. At $2 million, buyers typically order all three plus a general home inspection. Budget 10 to 15 days for inspections and review.
That time is already inside your 30-day escrow window, so the schedule has to be tight and organized from day one.
How to structure the 60-day execution plan for buying a $2 million Huntington Beach home
The plan has four steps, and they overlap. Step one: get your financing lined up before you list. That means a full preapproval for the purchase loan, a bridge loan or HELOC application if you need one, and a clear picture of your net proceeds at two or three sale price scenarios. Do not skip this step.
It is the foundation everything else rests on.
Step two: start your purchase search before you list. With a 58-day median days on market for $2 million-plus homes in Orange County, you need to know the inventory. Tour the neighborhoods, identify two or three homes that meet your criteria, and understand what a competitive offer looks like in each area.
You are not making offers yet. You are building readiness to move fast when the time comes.
Step three: list your home with a pricing strategy built for speed. In Huntington Beach, 19 days is the median time to an accepted offer across all detached homes. Price at market, not above it. A well-priced home in good condition in this market moves in the first two weekends.
A price cut in week three costs you time and negotiating leverage on both sides of the transaction.
Step four: once you have an accepted offer on your home, make your move on the purchase. If you have bridge financing or cash reserves, you can make a non-contingent offer. If you need a sale contingency, disclose it clearly and be prepared to negotiate the kick-out clause terms.
Open both escrows as close together as possible and coordinate the closing dates with both sets of sellers.
The goal is to close the purchase within a few days of your sale closing, or to use bridge financing to close the purchase first and pay off the bridge loan when your sale funds. Either path works. The choice depends on which home closes first and what your lender allows.
One practical note: the 30-day escrow window in Huntington Beach is tight. Every day counts. Have your inspectors lined up before you open escrow, have your loan documents ready to submit immediately, and have your agent coordinating with both escrow officers from day one.
What happens if your home does not sell on schedule
This is the question most people avoid, and it is the most important one to answer before you start.
If your home sits longer than expected, you face three risks: your bridge loan or HELOC costs more than planned, your purchase contingency triggers a kick-out, or you have to close the purchase without your sale proceeds and carry two mortgages temporarily.
Orange County had 4,987 active listings in the October 2026 report. That is a real inventory level, not a shortage. If your home is priced correctly and in good condition, it should move. Pricing it accurately from day one is the non-negotiable part.
An overpriced listing in a 19-day median market is the one thing that breaks the whole plan.
If a kick-out clause is triggered, you typically have 72 hours to remove your sale contingency or lose the purchase. That means you need to know in advance whether you can close without your sale proceeds. If the answer is no, be honest about that before you make a contingent offer, not after the clock starts.
A backup plan might be a short-term rental while you wait for the right purchase, or a rent-back agreement on your sale that gives you 30 to 60 extra days in your current home after closing. Rent-back agreements are common in Huntington Beach and can bridge a timing gap without bridge financing.
Discuss the option with your agent before you list.
The worst outcome is closing your sale, losing your purchase, and having to find a new home in a competitive market with your proceeds sitting in a bank account. That outcome is avoidable with preparation.
The plan above is designed to keep both transactions moving in parallel so you are never fully exposed on either side.
Selling and buying at the same time
Map out your sell-and-buy move before you list
One call covers your net proceeds, your next payment, and how to bridge both sides without owning two homes or none.
Book my sell-and-buy strategy call
Prefer to talk now? Call or text 714-500-7797 · Serving coastal Orange County since 2004
Questions clients ask about buying a $2 million Huntington Beach home
Is a 60-day close realistic after listing my Huntington Beach home?
Yes, if you define the 60 days correctly. Huntington Beach detached homes had a 19-day median days on market in the 90 days ending September 30, 2026, per CRMLS. Escrow closes in about 30 days or less after opening. That puts a typical sale at roughly 49 days from list to close. If your purchase escrow opens at the same time as your sale escrow, both can close within that window. The key is having your financing and your purchase shortlist ready before you list, not after.
Should I use a sale contingency, bridge loan, or HELOC when buying a $2 million Huntington Beach home?
It depends on your equity, income, and how competitive the purchase market is. A sale contingency is the lowest-cost option but the weakest negotiating position at $2 million. A bridge loan or an already-open HELOC gives you the ability to make a non-contingent offer, which is stronger. Bridge loans carry higher short-term rates, so confirm the cost with a lender. If you have enough liquid assets to close without sale proceeds, that is the cleanest path. There is no single right answer without knowing your specific numbers.
What mortgage payment should I expect on a $2 million Huntington Beach home?
At 7.40%, the 30-year fixed rate reported by the Freddie Mac survey on October 8, 2026, a $1.6 million loan (20% down on a $2 million purchase) carries a principal and interest payment of roughly $11,000 a month. Add property taxes at about 1.25% of assessed value, which on a $2 million home is about $2,083 a month, plus any HOA dues and insurance. The total monthly cost is significant. Run the full number with a lender before you set your purchase budget.
What coastal or flood zone issues should I check before buying at this price point?
Huntington Beach is a coastal city, and some areas near the Harbour channels, the Bolsa Chica wetlands, and the beach sit in FEMA Zone AE, which may require flood insurance as a lender condition. That cost needs to be in your monthly budget. Homes in the coastal zone may also need a Coastal Development Permit for future additions or structural changes. Check the permit history on any home you are considering, and review the natural hazard disclosure report carefully. A thorough inspection process, including sewer, termite, and roof, is standard at this price point.
How do I know if my current home will sell fast enough to fund the purchase?
Start with the median days on market for your specific neighborhood, not the citywide figure. South Huntington Beach detached homes averaged 12 days to an accepted offer in the recent CRMLS period. The northwest interior averaged 17 days. Downtown numbered streets ran closer to 35 days. Price your home at market from day one. Huntington Beach detached homes sold at 98.5% of original list price on average, which means the market is pricing accurately. An overpriced listing is the single biggest risk to your timeline on both sides of the transaction.
Are there tax implications I should know about when selling and buying at the same time?
Yes, and they can affect how much of your sale proceeds you keep. If you have lived in your home for at least two of the last five years, you may qualify for a capital gains exclusion on a portion of the gain. Prop 19 allows eligible homeowners to transfer their property tax base to a replacement home under certain conditions. A 1031 exchange is generally not available for a primary residence. These rules have specific requirements and deadlines. Confirm all the details with your CPA or tax advisor before you structure the transaction.
What to do right now
Here is what to do right now. Pull your current mortgage statement and calculate your approximate equity at two sale price scenarios, one at market and one 5% below. Then call a lender and ask specifically about bridge loan qualification and HELOC availability before you list. Start touring homes in the $2 million range in the neighborhoods you are considering so you know the inventory. Get a pricing opinion on your current home from someone who knows the Huntington Beach detached market at the street level. When all three of those pieces are in place, you are ready to list and buy at the same time with a real plan behind you, not a hope.
The next step
Ready to talk through your Huntington Beach move?
Tell me where you are in the process and I will map out your options, your numbers, and your timing. 15 minutes, zero pressure.
Schedule my free 15 minute call
Prefer to talk now? Call or text 714-500-7797 · Serving coastal Orange County since 2004
Know what Huntington Beach homes are really selling for
One short email each week: new listings, closed sales, and where prices are heading. Free, and easy to leave anytime.
Gantry Wilson · Gantry Wilson Group · Real Brokerage · Huntington Beach, CA · DRE# 01412779
Trusted. Local. Proven.